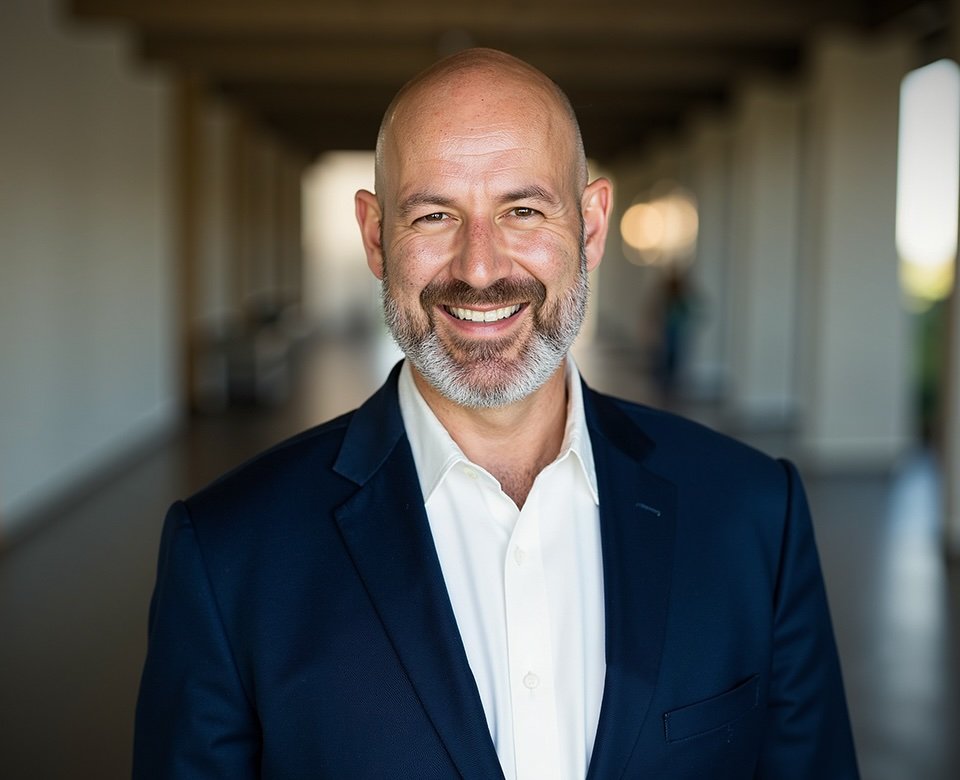
Frank Rohde  ·  San Francisco  ·  Advisor to B2B Technology Companies & Their Investors

Go-to-market is a craft.
Pricing is a discipline.
Enterprise deals are won by both.

I advise B2B technology companies and the private equity firms that back them on US market entry, pricing strategy, and sales execution. I approach each engagement from the perspective of having been an operator first, advisor second.

Frank Rohde
25+
Years in B2B technology
50+
Enterprise & growth clients
100+
Startups advised on pricing
17
Years as CEO living the challenges
Background

The advice comes from the operating seat, not the sidelines.

Today
Founder & CEO, Ownify — fintech reimagining the path to homeownership
2014–Now
Partner, Alchemist Accelerator — faculty for go-to-market & pricing
2009–2022
CEO, Nomis Solutions — sold to Symphony Technology Group
2001–2005
VP Products, FICO — predictive analytics & decisioning software for global banks
1999–2001
Co-founder, eCoverage — digital P&C insurance in 40+ states
Origins
Oliver Wyman — financial services strategy · The Wharton School, BS Economics

Most consultants have studied the playbook. I've run it, with payroll on the line and a board watching the numbers.

I started in financial services strategy at Oliver Wyman, then co-founded eCoverage, one of the first digital property & casualty insurers in the US. FICO recruited me to build its predictive analytics product line into a $15M+ ARR business serving banks globally. I then joined Nomis Solutions as part of the founding team, took it from $200K in first-year sales to the premier pricing platform for the world's top 100 banks and lenders, and as CEO led it to positive EBITDA before selling to Symphony Technology Group.

Along the way I raised capital from Bain Capital Ventures, August Capital, Accenture, and Silicon Valley Bank; repositioned the company through the 2008 credit crisis; re-platformed the business to SaaS; and negotiated seven- and eight-figure agreements with the most demanding procurement teams in North America, Europe, and Asia Pacific.

Born in Germany and built in Silicon Valley, I've lived the US market-entry journey myself, including a stint running product from London. Today, alongside leading Ownify, I advise a select number of companies and investors on go-to-market, pricing, and the enterprise deal table.

Advisory Practice

Three disciplines. One through-line: revenue quality.

My engagements center on the three core levers that most determine whether a B2B technology company builds durable enterprise value: market entry, value capture / pricing strategy, and scalable sales execution.

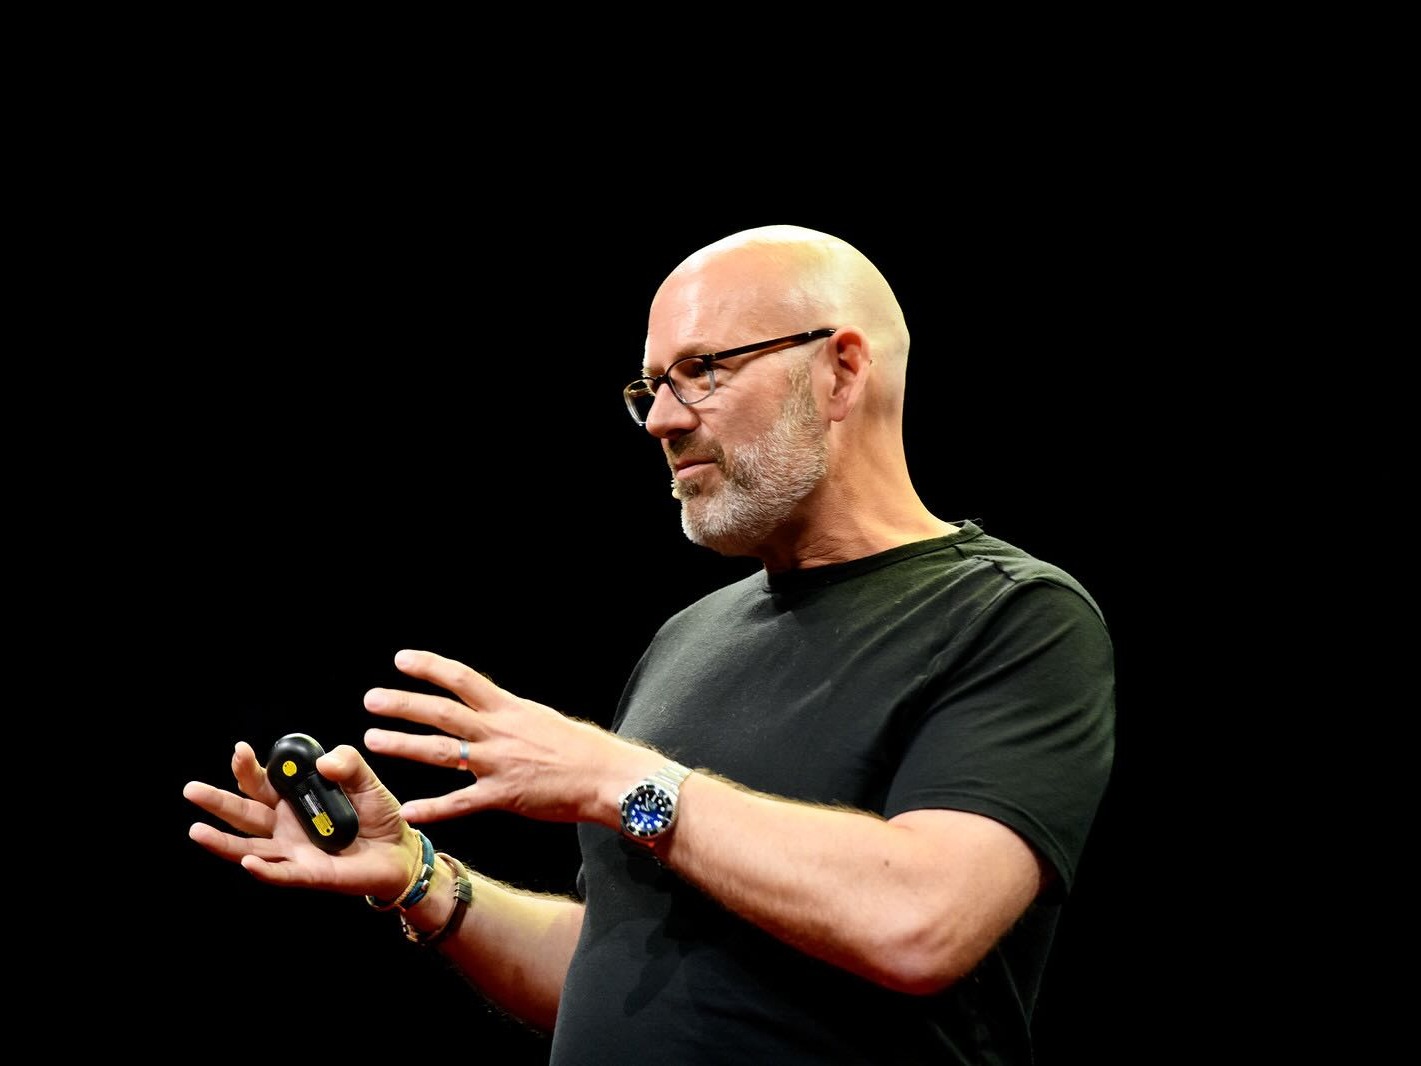
Frank Rohde speaking on stage
01

US Market Entry, Marketing & Sales

For European and international technology companies, the US market makes or breaks the valuation story. It is also unforgiving of imported playbooks. I help leadership teams localize positioning, sequence their entry, price for the US buyer, and design the sales organization a US enterprise motion requires: hiring profiles, compensation, territory design, and channel strategy.

For European & global firms entering the US
02

Pricing Strategy & Pricing Design

I ran a pricing-science company for thirteen years. Pricing is not a workshop topic for me; it is the business I built. I design pricing architectures for B2B software and AI companies: value metrics, packaging, price levels, discounting governance, and migration paths that raise net revenue retention without burning the installed base.

As resident pricing advisor at Alchemist Accelerator, I've helped 100+ startups and growth companies build and implement pricing models, from first price list to PE-grade pricing transformation. My clients have consistently been able to increase revenues and profits by 20%+ through thoughtful pricing strategy and execution.

For SaaS, AI & data companies at every stage
03

Large Enterprise Contract Negotiations

The last 10% of a large enterprise deal often determines 50% of its lifetime economics. I advise founders and CROs through the procurement, security, legal, and vendor-risk gauntlet of the Global 2000: deal structure, pricing concessions, multi-year commitments, and the terms that quietly preserve or destroy margin.

My reference point: negotiating seven- and eight-figure agreements with the largest banks in North America, Europe, and Asia-Pacific as a vendor CEO.

For founders, CROs & deal teams
Clients & Collaborations

My clients include blue chip enterprises as well as the startups growing into them.

I've worked with more than 100 enterprises, growth companies, and startups across North America, Europe, Asia-Pacific, and Central Asia, including Accenture, Oliver Wyman, Goldman Sachs, Wells Fargo, Bank of America, Royal Bank of Canada, Toronto-Dominion, Truist, Allianz, Westpac, BASF, and Bayer. At the same time, I work with early- and growth-stage companies entering the US market:

Alchemist Accelerator — startup advisory

A Partner at Alchemist Accelerator since 2014, I serve as CEO coach, investor, and faculty for the go-to-market and pricing curriculum. I've advised hundreds of enterprise startups across fintech, proptech, applied ML, voice AI, legal tech, risk management, lending, and mortgage technology, including Veritus.ai, Hubtalk.ai, RED Atlas, Torus, Data Culture, Lendsnap, Tyche, Perfect Price, and many more.

Silkroad Innovation Hub — Central Asia to Silicon Valley

Through the Silkroad Innovation Hub in Palo Alto, I mentor and advise technology companies from Central Asia on US market entry, pricing, and enterprise sales. It's some of the most rewarding work I do: helping a new generation of founders compete credibly in Silicon Valley and with US enterprise buyers.

For Private Equity

Pricing and go-to-market are the cheapest EBITDA you'll ever buy.

I work with private equity investment groups across the deal lifecycle: commercial and pricing diligence pre-close, then value creation post-close: pricing transformation, US expansion for European portfolio companies, sales organization redesign, and renegotiation of major enterprise contracts at renewal.

I've worked with major US and European sponsors and their portfolio companies on revenue and EBITDA increases through pricing and sales strategy. A point of net revenue retention or realized margin is worth far more at exit than it costs to earn.

Focus Area

Pricing AI products, when every answer costs you money.

For twenty years, software pricing rested on a comfortable assumption: marginal cost is zero. AI broke that assumption. Every inference consumes tokens, every token has a price, and your customers' enthusiasm now shows up in your cost of goods sold. I advise AI-native companies and software companies embedding AI on pricing architectures that scale value capture with value delivery, without letting usage variance eat the gross margin your investors are underwriting.

Token economics & margin design

Modeling true cost-to-serve across models, prompts, and workloads; designing price metrics, usage tiers, commitments, and overage structures that keep gross margin predictable as inference costs and customer behavior shift underneath you.

From seats to outcomes

When AI does the work, per-seat pricing prices you against your own product. I help teams migrate to hybrid, usage-based, and outcome-based models, including how to sequence the transition across an enterprise installed base without triggering churn or a repricing revolt.

AI terms in enterprise contracts

Enterprise buyers are learning to procure AI, and their playbooks are brutal. I advise on consumption commitments, cost-indexation and pass-through clauses, benchmarking rights, and SLAs for non-deterministic systems, so the contract protects your economics for the full term, not just at signature.

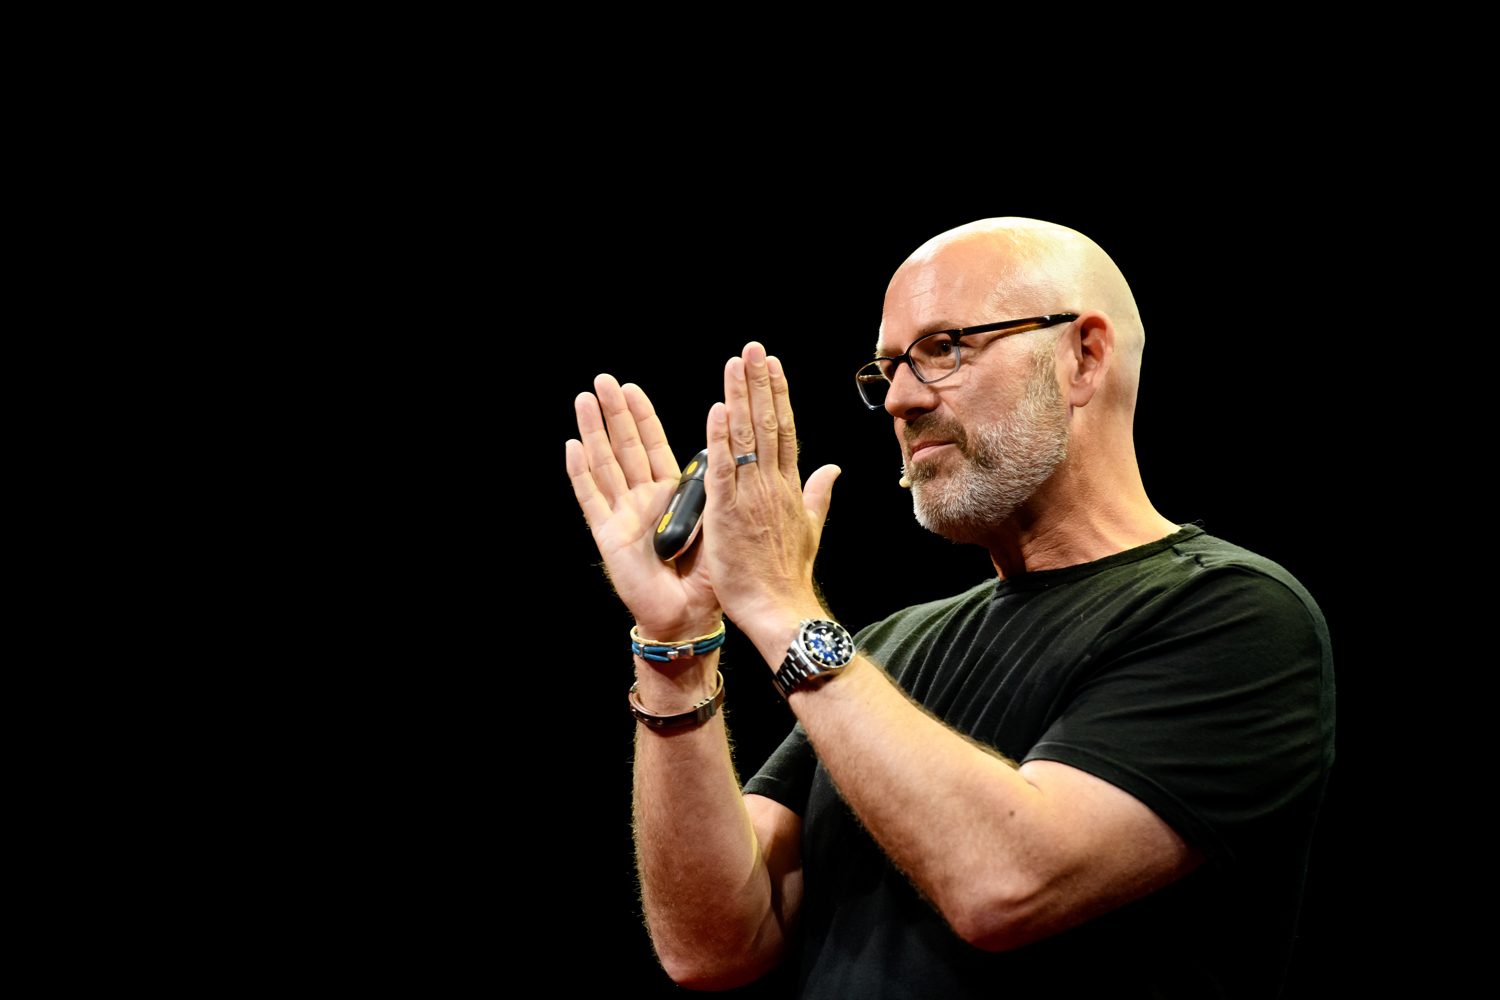
Frank Rohde on the TEDx stage
On the TEDx stage
Speaking

From the TEDx stage to intimate management team sessions.

Believe it or not, talks on pricing in the age of AI, go-to-market strategy, and enterprise sales can be engaging! I generally pair operator war stories with frameworks audiences can use the next morning.

Recent TopicsPricing AI when every answer has a cost  ·  The end of per-seat pricing  ·  US market entry for European tech  ·  The true cost of homeownership
Perspectives

Three arguments on pricing in the age of AI.

These are the topics I'm currently working through with clients.
01 · Business Models

The Seat Is Dead. What Are You Charging For Now?

Per-seat pricing was never really about seats. It was a proxy: a crude but reliable stand-in for value in a world where software made humans more productive, and more humans meant more value.

AI inverts the proxy. When an agent resolves the support ticket, drafts the contract, or reconciles the ledger, value delivered goes up while seat counts go down. A vendor pricing per seat is now paid less for building a better product. The best AI companies will cannibalize their own seat counts, and the pricing model must be rebuilt before that happens, not after the renewal where a customer asks why they're paying for 400 licenses and 60 humans.

The uncomfortable answer is that there is no single successor metric. Work units, resolved outcomes, consumption with committed floors, value-share on measurable savings: each fits a different buyer, budget process, and trust level. The craft is in matching metric to market. Enterprises will not sign an uncapped outcome-based deal from a Series B vendor, but they will sign a hybrid: platform fee for predictability, usage for scale, an outcome kicker where ROI is provable. The companies that get this right won't just protect revenue as seats disappear. They'll capture, for the first time, the actual economics of the work their software does.

02 · Unit Economics

Your Gross Margin Is Now a Pricing Decision

Software spent two decades enjoying an economic miracle: 80%+ gross margins that nobody had to manage. AI ended the miracle. Marginal cost is back, and most pricing models haven't noticed.

Every AI feature ships with a meter running. Token consumption varies wildly by customer, use case, even prompt style. Charge a flat subscription against a variable cost and you have written your customers a free option. Your heaviest users, often your flagship logos, become your least profitable accounts. I've seen AI products where the top decile of users consumed 20x the median. Under flat pricing, that's not a power-user success story; it's a structural margin leak the CFO will eventually find.

This is a pricing-design problem, and it's solvable, but only deliberately. It means knowing cost-to-serve at the account level, not the blended average. It means fair-use thresholds, committed-usage tiers, and overage terms that are commercially graceful rather than punitive. It means deciding which margin risks you keep (model efficiency gains you can capture) and which you share (customer-driven volume). And it means resisting the venture-funded temptation to price AI at a loss, because negative-margin revenue doesn't scale into a business; it scales into a bigger problem. In the AI era, gross margin isn't an accounting outcome. It's an architecture choice.

03 · Enterprise Deals

Who Pays for Intelligence? Negotiating AI Contracts with the Global 2000

Enterprise procurement has priced software for thirty years. It has priced intelligence for about three. The result is a negotiation table where neither side fully understands the cost structure being contracted, and the vendor usually pays for the ambiguity.

Large buyers are importing cloud-era tactics into AI deals: flat, all-you-can-eat pricing while their own AI usage grows unpredictably; multi-year price locks on services whose underlying costs (model pricing, context lengths, agentic workloads) move quarterly; benchmarking clauses that treat a reasoning system like a commodity SaaS module. Vendors, desperate for the logo, sign terms that transfer all of the usage risk and none of the upside. Three years in, the contract everyone celebrated is a margin trap nobody can exit.

The negotiation frontier is shifting from price level to risk allocation. Who absorbs model-cost movements, and who benefits when inference gets cheaper? What is a “unit” of AI work, contractually, and who measures it? Does a committed-spend structure flex across models and use cases, or lock the buyer into yesterday's architecture? These clauses, not the headline discount, determine deal economics. My advice to vendors: negotiate the meter before you negotiate the number. And to the PE firms underwriting these revenue streams: read the AI terms in the top ten contracts first. That's where the real quality of earnings now lives.

Engage

The best time to fix pricing was before the last deal. The second-best time is now.

Whether you're a European company weighing US entry, a founder staring down a procurement gauntlet, or an investor pressure-testing your next platform deal, let's talk.

Direct booking via Calendly · Advisory sessions also available via Intro